
Anyone who drives in Texas has a story. A sudden hailstorm that turned a clean hood into a golf ball. A highway merge that went wrong at exactly the wrong moment. A driver who hit a parked car and simply drove away. Most of these stories end better when the driver has the right coverage, and much worse when they do not. This guide explains auto insurance in plain words, using the coverage topics described by Champions Insurance, an independent agency based in Friendswood.
Why auto insurance matters more than most people think
For many people, a car or truck is the biggest purchase after a home. It also carries a risk that few other possessions do: when you drive, you can hurt other people and damage their property. A single accident can mean medical bills, repair costs, lost income and even a lawsuit. Auto insurance exists to move some of that financial weight off your shoulders. It will not prevent an accident, but it can stop one bad day from becoming a decade of debt. Champions Insurance describes auto coverage as protection for both you and your vehicle, and that simple idea is a good starting point.
Who is Champions Insurance?
According to its own website, it is an independent insurance agency with an office in Friendswood, Texas, licensed in Texas and serving clients across the state. It offers personal insurance, such as home, auto and watercraft, as well as business coverage. Treat this as Unit 1 of your research: understand who you are talking to before you share details. An independent agency generally works with more than one insurance company, which can give you more choices, though you should ask exactly which carriers are available. Check the current details and hours on the official page of Champions Insurance before you call.
Bodily injury liability: protecting others, and yourself
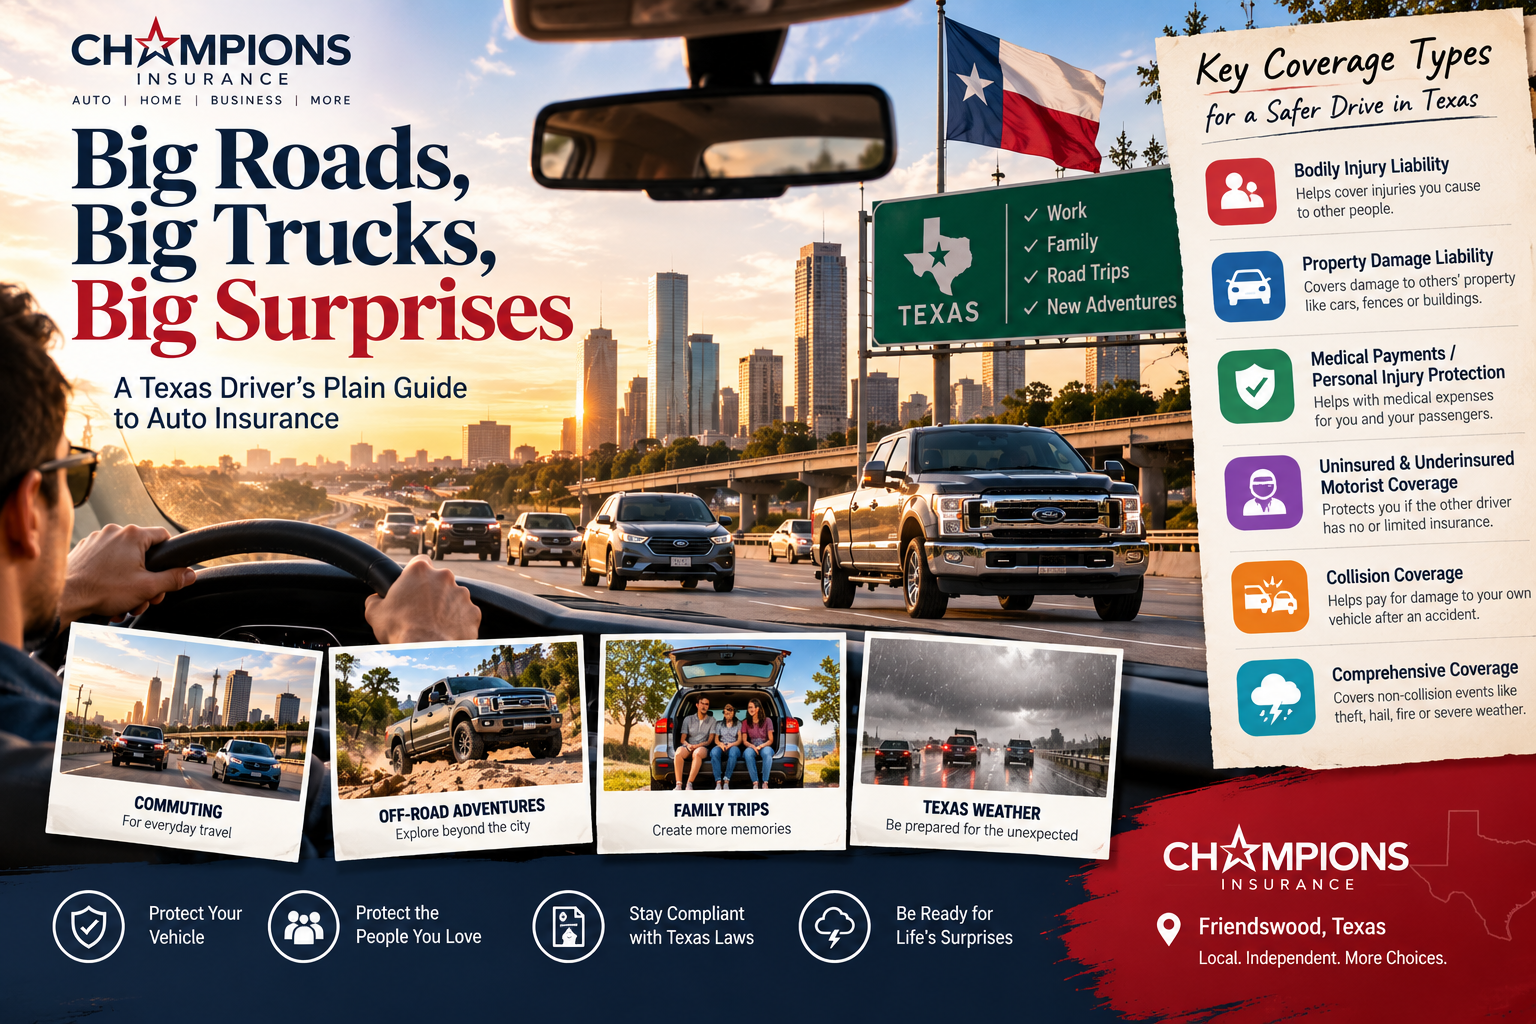
This is the coverage most people have heard of, and also the one most often misunderstood. Bodily injury liability helps pay for injuries you cause to other people in a covered accident, up to the limit you choose. It matters because a moment of distraction, such as a text message or a fussy child in the back seat, can lead to a crash. If someone is hurt, you may be held financially responsible. The agency’s page also suggests buying enough coverage to protect your assets, and considering an excess liability policy for extra limits. Ask Champions Insurance how different limits would work for your situation.
Property damage liability: the things you can hit
When you cause an accident, the damage is not only to people. Your vehicle might hit another car, a fence, a mailbox or even part of a building. Property damage liability covers the cost of that damage to other people’s property, up to your limit. The required amount, if any, varies by state, and sometimes the insurer sets a standard amount. When you review your options with Champions Insurance, compare the property damage limit against the value of the cars on the roads you drive.
Minimum coverage: legal is not the same as enough
Every state sets rules for the minimum insurance you must carry, and Texas is no exception. Commonly cited Texas minimums are sometimes written as thirty, sixty and twenty five, meaning limits for injury per person, injury per accident and property damage, but you should confirm current numbers with the Texas Department of Insurance. Treat this as Unit 1 of your safety margin: the legal minimum is a starting line, not a finish line. The agency’s page notes that some policies simply meet legal requirements, while others go further. Talk to Champions Insurance about what a higher limit would cost compared with the risk of paying a gap yourself.
Medical payments and personal injury protection
After an accident, health care costs can reach thousands of dollars, and your health plan may not cover everything. Medical payments coverage, or personal injury protection depending on where you live, can help with some medical and funeral expenses for covered drivers and passengers. In Texas, insurers generally must offer personal injury protection, and you usually have to reject it in writing if you do not want it, but check the current rules rather than relying on memory. Think about who rides with you: children, friends, coworkers. Ask Champions Insurance to explain which of these options apply to your policy and how they interact with your health insurance.
Uninsured and underinsured motorist coverage
This one protects you from other people’s choices. If a driver who hits you has no insurance, too little insurance or simply drives away, you could be left paying for your own injuries and damage. Uninsured and underinsured motorist coverage may compensate you for bodily injury and lost wages in those situations, depending on your policy. The agency’s page says that this problem happens more often than people expect. When you speak with Champions Insurance, ask how this coverage works with your own liability limits and whether property damage is included.
Collision and comprehensive: protecting your own vehicle
Physical damage coverage is what protects your own car or truck. Collision helps when your vehicle is damaged in an accident. Comprehensive helps with damage from other causes, such as theft, fire or severe weather, depending on your policy. In Texas, hail and storms are a real concern, so this part deserves attention. Treat this as Unit 1 of your vehicle protection plan: look at your car’s value and your finances honestly. The agency’s page says this coverage is optional if your vehicle is paid off, but worth considering if you want full protection. Ask Champions Insurance what is included and excluded for your vehicle.
Rental coverage and loss of use
When your car is in the shop, life does not pause. You still need to get to work, school and appointments. Rental coverage, sometimes called loss of use, helps pay for a temporary replacement vehicle or other transportation if your car is being repaired or replaced after a covered loss. The agency describes it as an inexpensive option available with different daily limits. Think about how many days you could manage without your vehicle, and ask Champions Insurance which daily limit makes sense for your routine.
Choosing limits without guessing
Picking limits can feel like guessing, but a simple method helps. Start with what you own: savings, home equity, future income. The more you have to lose, the more protection you may want. Next, consider your risk: how much you drive, where you drive and who else drives your car. Then look at the cost of higher limits, which often rises less than people expect compared with the extra protection. Write down two or three options and compare them side by side. When you discuss limits with Champions Insurance, bring your list and ask which option protects you best.
Deductibles: the amount you pay first
A deductible is the amount you pay out of your own pocket before insurance covers the rest of a claim. A higher deductible usually lowers your premium, but it means more cost when something goes wrong. A lower deductible does the opposite. The right choice depends on how much cash you could comfortably find on a bad day. If a thousand dollars would cause real stress, a very high deductible may not suit you. Some people choose different deductibles for collision and comprehensive. Ask Champions Insurance to show you the premium difference between two deductible levels, and pick one that feels realistic.
How to prepare for a quote
Getting a quote is easier when you have your information ready. Gather your driver’s license details, your vehicle information, including the make, model, year and identification number, and your current policy if you have one. Note who else drives the vehicle, and your approximate yearly mileage. Think about how you use the car: commuting, errands, business or family trips. The agency’s page describes a simple process: fill out a form, review your options with the team and get the coverage you need. Avoid putting sensitive private details into open text boxes. When you contact Champions Insurance, share only what is asked and keep your own notes.
Questions to ask an agent
Good questions turn a sales call into a useful conversation. Which companies can you quote for me? What are the limits and deductibles in each option? What exactly is excluded? How do uninsured motorist and medical coverage work together? Does the policy include rental coverage and at what daily amount? How do I report a claim and what happens next? What discounts might apply, and what must I do to keep them? Write the answers down and compare them. If something is unclear, ask for it in writing. A good agent at Champions Insurance should be comfortable explaining the details until you understand them.
Review your policy every year
Your life changes, and your policy should change with it. A new job with a longer commute, a teenage driver, a newly paid off car, a move to another city or a new vehicle can all change what you need. Treat this as Unit 1 of your yearly habit: schedule a short policy review on your calendar. The agency’s website lists a policy review service, which shows that this is a normal thing to ask for. Bring your current documents and ask what has changed. A quick conversation with Champions Insurance once a year can catch gaps before they become expensive problems.
What to do after an accident
Stay calm and take these steps in order. Check for injuries and call emergency services if anyone is hurt. Move to a safe place if possible and turn on your hazard lights. Exchange information with the other driver and take photos of the scene, the vehicles and any damage. Get a police report if appropriate. Do not argue about fault at the scene. Contact your insurer or agent promptly to report the claim, and keep every receipt and message. The agency’s website offers a claim reporting page. Having the number for Champions Insurance saved in your phone beforehand makes the first hour far less stressful.
Mistakes that cost drivers money
A few errors appear again and again. Buying only the legal minimum and hoping for the best. Skipping uninsured motorist coverage to save a little. Choosing a deductible that is too high to afford. Forgetting to update the policy after a big life change. Assuming that all policies with the same price give the same protection. Waiting too long to report an accident. Cross these off before you buy. Whether you choose Champions Insurance or another provider, careful comparison beats a rushed decision every time.
A word of honesty
This post is general information, not insurance or legal advice. The coverage descriptions here follow the agency’s public auto insurance page, and other details come from general knowledge, so they may not match your policy. Laws, minimums and rules change, and they differ from state to state. Champions Insurance says it is licensed in Texas, so it may not be able to help you elsewhere. Always read your actual policy and confirm important points directly with an agent or the Texas Department of Insurance. And if you decide that Champions Insurance is not the right fit for you, that is a perfectly sensible outcome.
Final thoughts
Auto insurance is not exciting, but it is one of the quiet foundations of a stable life. Learn what each coverage does, choose limits that match what you could lose, keep your deductible realistic and review your policy every year. Ask questions until the answers make sense, and keep your documents tidy. If you live in Texas and want a conversation with a local team, you can visit Champions Insurance, request a quote and compare it with other options. The goal is simple: when the unexpected happens on the road, you want to be prepared, not surprised.