
Ask ten travelers about travel insurance and you will hear ten confident opinions, and at least half of them will be wrong. Some people swear it is a waste of money. Others assume it fixes every problem, from a rainy week to a lost mood. Both beliefs can hurt your wallet. The truth sits in the middle, and it is full of small details that decide whether a claim gets paid. In this post we will go through the most common myths, one by one, and look at how a provider like Faye fits into the picture. No hype, no fear, just plain facts and sensible questions.
Why myths spread so easily
Insurance is boring until the day it is not. Most people only meet it in a stressful moment, so they learn from stories rather than from documents. A friend’s claim got denied, so the whole industry seems unfair. Another friend’s claim got paid, so everything seems covered. Both stories leave out the rules that decided the outcome. Treat this as Unit 1 of your learning: separate stories from policy wording. Whenever you hear a strong opinion, ask which policy, which trip and which reason. Even a modern provider such as Faye has conditions, and those conditions matter far more than any rumor. The cure is simple curiosity and a habit of checking the source, which costs nothing and takes only a few minutes.
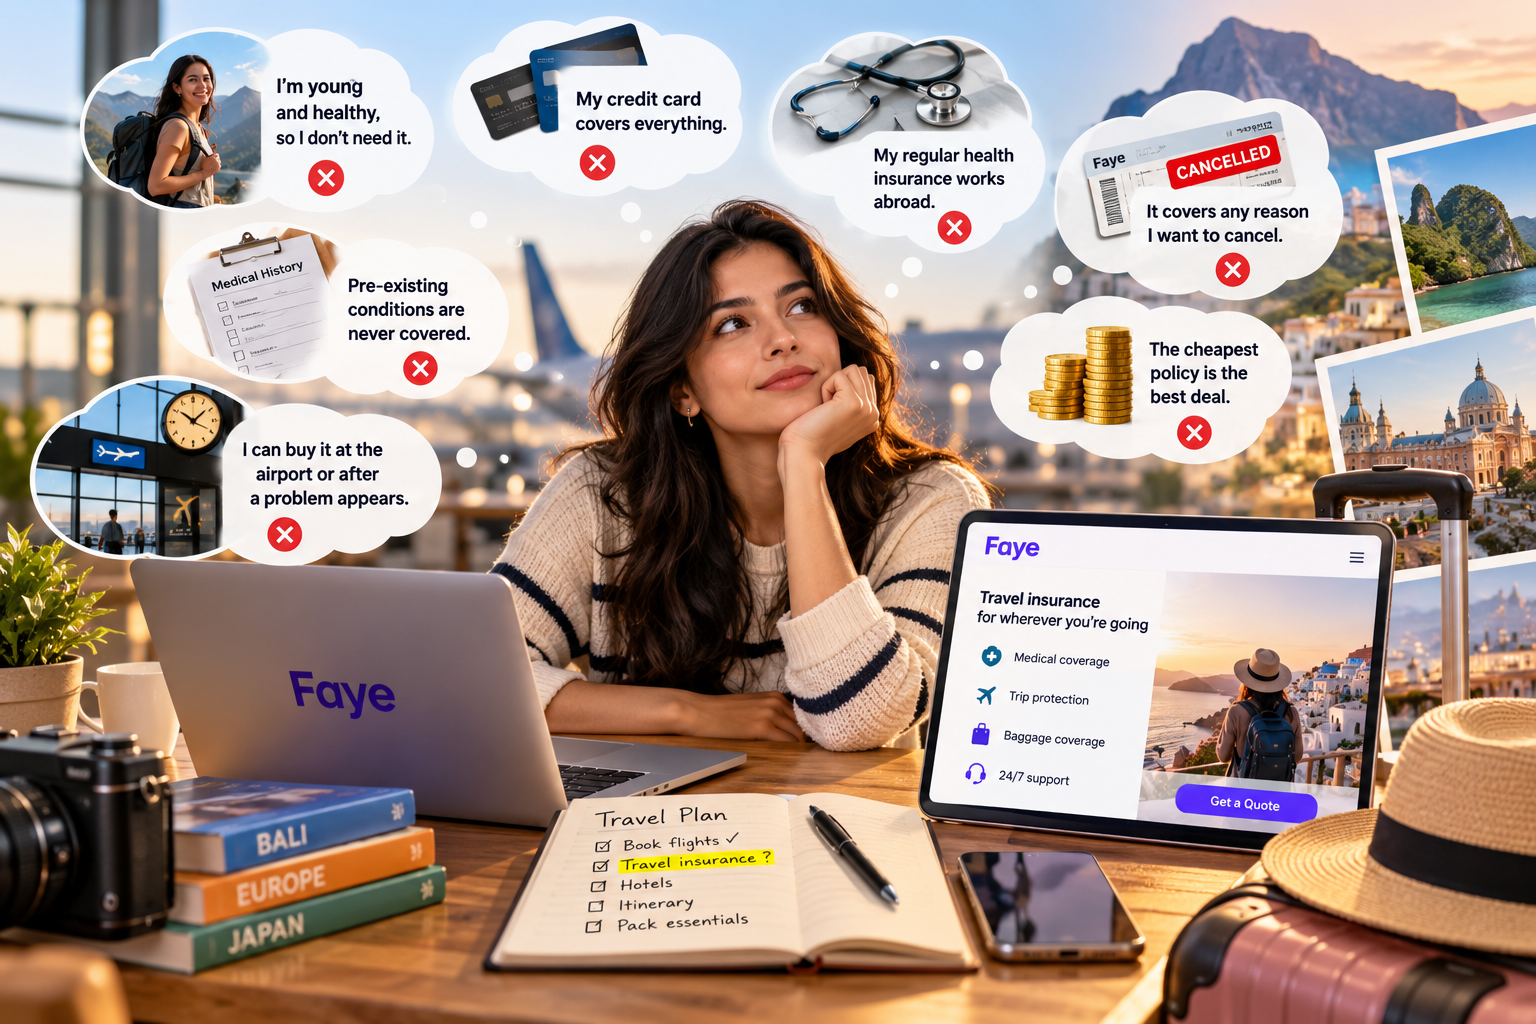
Myth one: I am young and healthy, so I do not need it
Good health is wonderful, but travel problems rarely ask about your fitness. A broken ankle on a hike, a stomach infection, a sudden appendix attack or a motorbike slip can happen to anyone. Medical care abroad can also be expensive, and you may have to pay upfront in some places. Beyond health, there are cancelled flights, lost bags and stolen phones. Being young and healthy lowers one kind of risk, not all of them. Instead of asking whether you will get sick, ask how much you could afford to lose. If the answer worries you, look at what Faye offers and compare it with your budget.
Myth two: my credit card covers everything
Many cards offer useful travel benefits, such as trip delay or baggage protection. But these often come with caps, conditions and gaps. You may need to pay the full trip with that card, and medical cover abroad is often limited or missing. Some benefits apply only to certain events, and the paperwork can be demanding. The practical move is to read your card’s guide to benefits and write down what it truly includes. Then compare that list with a policy from Faye. If your card already covers the same risks well, you might skip extra cover. If it leaves holes, a standalone policy may help.
Myth three: my regular health insurance works abroad
Many people assume their usual plan follows them everywhere. In reality, many domestic plans offer limited or no cover outside the home country, or they treat overseas care very differently. Even when some cover exists, it may not include evacuation, which can be very costly in remote places. It may also not cover bringing you home. Call your health insurer before you travel and ask direct questions: is emergency care abroad covered, do I pay first, and what about evacuation? A quick five minute phone call can reveal gaps you never knew existed. Treat this as Unit 1 of your gap check. Whatever remains uncovered is where a travel policy from Faye could help.
Myth four: it covers any reason I want to cancel
This one causes real disappointment. Standard travel insurance covers cancellations only for specific listed reasons, such as certain illnesses, injuries or other covered events. Changing your mind, feeling tired or finding cheaper tickets later is usually not on the list. Some providers sell a pricier add-on called cancel for any reason, which has its own rules, and usually reimburses only part of your costs. Reviewers mention such options for Faye as well, but you must check current terms. Before buying from Faye, read the list of covered reasons and decide whether you want a broader, costlier add-on.
Myth five: pre-existing conditions are never covered
The truth is more nuanced. Many policies exclude pre-existing conditions by default, but some offer a waiver or special cover if you meet certain conditions, usually involving how soon you buy after your first trip payment and whether you are medically able to travel at that time. One review of Faye mentions a fourteen day window, which you should verify yourself. The key idea is timing. Buy late and you may lose the option. When you request a quote from Faye, read how the policy defines a pre-existing condition and keep a copy of those words.
Myth six: I can buy it at the airport or after a problem appears
Insurance works only for events that have not happened yet. If a storm is already forecast, a strike is announced or you already feel unwell, a new policy may not cover that known situation. Reviewers also note that Faye does not let you buy once your trip has begun. The safest time to buy is soon after your first payment, because early cover can protect your deposits and may unlock more options. Put a reminder in your phone on booking day. Then open Faye, enter your dates and look at the quote while everything is still calm.
Myth seven: the cheapest policy is the best deal
A low price is attractive, but the number alone tells you little. Cheaper cover may have lower medical limits, higher deductibles or tighter exclusions. Premium also changes with trip cost, length, age, destination and add-ons, so quotes are not always comparable. The right method is side by side comparison: same dates, same trip cost, same medical limit, similar add-ons. Then read the exclusions. Treat this as Unit 1 of your price test: value equals cover divided by conditions, not price alone. When you check Faye, remember that paying slightly more for a clearer, broader policy can be the smarter move.
Myth eight: claims are always denied
Some travelers say insurers never pay. In reality, many claims are paid, and many denials happen for avoidable reasons: missing receipts, late notice, ignoring policy steps or events that were not covered. Strong records make a huge difference. Keep every receipt, report and message. Get written proof from airlines, hotels or police when relevant. Contact your insurer early and follow the instructions. Be truthful and consistent. None of this guarantees payment, but it removes the most common excuses. If you choose Faye, read the claim process before your trip so you know exactly what to do under stress.
Myth nine: short trips do not need cover
A weekend away feels low risk, yet short trips can be just as exposed. A medical problem or cancelled flight on a three day trip costs the same as on a three week trip, and the ratio of prepaid costs to trip length can even be higher. On the other hand, if your trip is cheap, refundable and close to home, you may reasonably skip cover. The question is not how long you travel, but what you stand to lose. Compare the possible loss with the price of a quote from Faye, and let that comparison decide.
Myth ten: adventure activities are automatically included
If you plan hiking, diving, skiing or anything risky, do not assume. Many policies limit or exclude certain activities, or require an add-on. Reviewers describe Faye as flexible for some adventurous plans, but the specifics, altitude limits and sport lists matter, and they change. Read the activity section line by line. If your activity is not listed, ask in writing. Keep the reply. Treat this as Unit 1 of your adventure checklist: never assume your sport is included. Before booking an adventure trip, confirm the details with Faye and compare them with your plan, not with a general impression.
Three imaginary trips, three different answers
Cover decisions depend on the trip, so consider three simple examples. First, a cheap weekend city break with refundable bookings and a short flight: the possible loss is small, and many people could reasonably skip a policy. Second, a two week family holiday with prepaid flights, hotels and tours: here a cancellation or medical event could cost a lot, so cover deserves serious thought. Third, a month of hiking in remote areas: medical and evacuation limits, activity rules and eligibility become the main questions. Look at your own plan beside these examples, then check what Faye says about each risk you care about before deciding.
A simple way to test any claim you hear
Next time someone tells you a travel insurance fact, run a quick test. First, ask whether it came from the policy wording or from a story. Second, ask which provider, which plan and what date. Third, check whether the rule is about covered reasons, limits or timing. Fourth, look up the current policy on the official page. Fifth, write down the answer. This habit protects you from both blind trust and blind distrust. It also works on this very blog. If something here differs from the current terms of Faye, trust the official documents and treat this post as a starting point.
How to talk to a provider without feeling lost
Many people avoid asking questions because they fear sounding silly. Questions are exactly how you protect yourself. Keep them short and specific. Ask what is covered for your situation, what is excluded, what the deductible is, how claims are filed and how long they usually take. Ask about eligibility based on your residence. Write down who answered, the date and the reply, and save any email in your travel folder. If an answer feels vague, ask for the exact policy wording. A good provider such as Faye should be able to point you to the page or document that supports its answer.
What good preparation looks like
Preparation is mostly small, repeatable actions. Buy early, read the policy and save the support details. Keep digital copies of your passport, bookings and receipts. Learn the claim steps before you leave. Note the eligibility rules based on where you live, because some providers serve only certain residents. Check whether your credit card or health plan already covers parts of your trip. Share the plan with a family member. This takes less time than choosing a hotel. When you finally open Faye, you will know exactly which questions to ask and which answers you need.
A word of honesty
This is not insurance advice, and no blog can replace the policy itself. The facts here come from reviews and general industry practice, and they may be out of date or may not match your situation. Providers change terms, and availability depends on where you live. In particular, some reviews say Faye serves only certain residents, so check eligibility first. If you have a medical condition or a complicated trip, speak to a licensed agent or to the insurer directly. And if you decide that Faye is not right for you, that is a perfectly good outcome of careful thinking.
Final thoughts
Myths survive because they sound simple, but travel insurance is a set of rules, limits and timing. Learn those rules and you will make calmer decisions, whether you buy cover or not. Question confident claims, read the wording, compare quotes fairly and keep your records tidy. If the terms fit your trip and your home country, you can open Faye and see a real quote with open eyes. If they do not, walk away without guilt. Either way, you will have replaced guesswork with facts, and that is the best protection a traveler can pack. Make one small promise to yourself before your next trip: check the facts first, then decide. A clear head always beats a confident rumor.